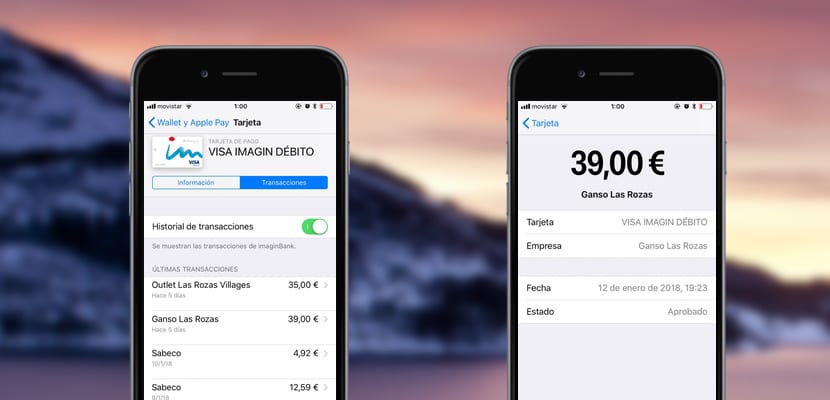
Apple Pay launched in India on September 30, the company confirmed. The service has a limited initial scope: it only supports Visa and Mastercard credit cards issued by Axis Bank, excluding, for now, the national RuPay network and the UPI system. landing in India It occurs in a market where digital payments have a very different appearance than in Europe or the United States.
The arrival of Apple Pay in India doesn't mean that any iPhone user can pay at any store. Availability depends on the issuing bank being integrated, the card being compatible, and the terminal or online store accepting the service. It's a bank-by-bank model which requires successive agreements and which, in practice, can translate into an irregular experience during the first few months.

A limited debut with Axis Bank

In this first phase, Axis Bank is the only announced issuer. Customers with eligible credit cards from Visa and Mastercard You can add them to Apple Wallet from the latest version of your bank's app or from the iPhone's Wallet app. Once added, the card can be used for contactless in-person payments, in-app purchases, and online transactions.
Apple Pay retains the benefits associated with the card, so the user continues to receive the benefits and rewards The service works at terminals that accept NFC payments and at digital merchants that have enabled this payment method. If the merchant has not integrated Apple Pay, the transaction will not be completed even if the card is valid.
Requirements, devices and payment method
To use Apple Pay in India you need a iPhone XR or later with iOS 18 or later. For the watch, you need an Apple Watch Series 6 or later with watchOS 11 or later, paired with an iPhone XR or later. The service also works on iPad, while Mac compatibility will arrive later, with no specific date yet.

- iPhone: XR model or later with iOS 18 or later.
- Apple Watch: Series 6 or later with watchOS 11 or later and paired with a compatible iPhone.
- iPad: It allows purchases in apps and websites, in addition to other compatible features.
- Mac: Apple has announced that support will arrive soon, but has not specified when.
In a store, the user must double-click the side button or the Home button, authenticate with Face ID, Touch ID, or the device passcode, and hold the top of the iPhone or Apple Watch screen near the contactless reader. Online purchases do not require repeatedly entering card details, address, or billing information. Apple states that this is not required. PIN or OTP when paying with Apple Pay.
Security and privacy
Apple maintains that the actual card number is not stored on the device or its servers, nor is it shared with merchants. Instead, a device account number encrypted and stored in the terminal's secure element. Mastercard and Visa have emphasized that their tokenization technology protects each transaction with a unique token.

This approach aims to reduce the risk of fraud and prevent bank details from circulating with each purchase. For the user, the result is an additional layer of privacy, although its functionality still depends on the... banking infrastructure and the agreements with each entity. It is not a standalone wallet, but a system that relies on existing cards.
Merchants, apps, and payment providers
Apple says Apple Pay will be available at millions of Indian merchants thanks to agreements with payment service providers such as Cashfree, JusPay, Mswipe, Paytm, PayU, Pine Labs, Razorpay and WorldlineAmong the stores and apps mentioned in the launch are Apple Store, Blinkit, Chaayos, Comet, Croma, Interflora, Ixigo, Le15 Patisserie, Reliance brands, Tata 1mg and Zomato.
The list of participating merchants does not equate to universal coverage. A physical store requires a compatible card reader; an app or website requires the merchant to offer Apple Pay at checkout. Therefore, the experience may vary between establishments and participating businesseseven within the same city. Apple expects to add more banks, retailers, and apps over time.
The standoff with UPI and the commissions
India is a special case because a large portion of digital payments are channeled through UPI, a state-backed system that allows money to be transferred between bank accounts without relying on cards. Apple Pay, on the other hand, competes in the card payments arena, a smaller segment. This difference explains why the launch isn't intended to displace Apple Pay. UPI Immediately.

Several reports indicate that Apple is seeking a commission of around 20 basis points per transaction, a figure that would fit its model in other markets but which Indian banks are viewing with caution. HDFC Bank, ICICI Bank, and SBI Card are not participating in the launch as negotiations on the financial terms continue. Axis Bank is opening the door to a service that, for now, depends on a issuer only.
What does it mean for Europe and for the user?
Apple Pay is available in more than 90 countries and regions and has over 11.000 banking and network partners worldwide. Its launch in India expands that presence, but it doesn't automatically change card eligibility outside the country. In Europe, as in other markets, each institution decides whether to participate and which cards it accepts; compatibility with Axis Bank in India doesn't automatically transfer to other markets. other European countries.
For a European user, the news primarily serves as a reference point for how Apple is deploying its service in markets where mobile payments are already heavily influenced by local systems. The company maintains its commitment to privacy, tokenization, and the absence of PINs or OTPs, but adoption will depend on the commercial acceptance, agreements with banks and competition from public alternatives.
The launch of Apple Pay in India is, in practice, a first step More symbolic than massive: it arrives with Axis Bank, Visa and Mastercard cards, recent devices, and a network of merchants under construction, while UPI and RuPay are left out of the initial equation. The company gains a foothold in a key market, but its growth will depend on convincing more banks, expanding acceptance, and fitting its fees into an ecosystem where card payments are not the norm. For users, the promise is clear: pay without PINs or OTPs and with tokenized data; the actual reach, however, remains to be seen.